 Est. 2003
Published by Bobby Gwynn | Artistic Construction | Serving Cherokee, Cobb & Fulton Counties
If you've searched "what salary do you need to build a house," you're asking a smarter question than most people start with. You're not just asking what building costs, you're asking whether you can actually afford to build. That distinction matters, and most online guides skip it entirely.
Here's the direct answer: in the North Atlanta suburbs, most lenders want to see a household income of at least $75,000–$85,000 to finance a modest new build in Cherokee County. That's one of the lower minimum salary thresholds in the metro area. Larger homes, premium communities like Alpharetta or Milton, and higher debt loads all push that threshold up. The sections below show you exactly how the math works.
What Salary to Build a House: Income-to-Budget Breakdown
The table below translates household income directly into a realistic build budget. Every figure assumes a 20% down payment, a back-end DTI of 43%, and a construction loan rate of 6.5–7.5%.
| Household Income | Est. Max Loan | Recommended Build Budget | Approx. Home Size (Mid-Range Finish) |
|---|---|---|---|
| $75,000 | ~$285,000 | $250,000–$270,000 | 1,400–1,600 sq ft |
| $100,000 | ~$375,000 | $330,000–$355,000 | 1,700–2,100 sq ft |
| $125,000 | ~$465,000 | $415,000–$440,000 | 2,100–2,600 sq ft |
| $150,000 | ~$560,000 | $495,000–$530,000 | 2,500–3,100 sq ft |
| $175,000 | ~$650,000 | $575,000–$615,000 | 2,900–3,600 sq ft |
| $200,000+ | ~$750,000+ | $660,000–$700,000+ | 3,300–4,200+ sq ft |
Assumptions: 20% down payment, 43% DTI, 6.5–7.5% construction loan rate, no significant existing debt. Planning estimates, not loan approvals.
Don't see your income range? Contact Artistic Construction for a free estimate tailored to your goals.
How Lenders Calculate the Salary Required for Home Construction
DTI, or debt-to-income ratio, is the number lenders use to determine how large a monthly payment you can carry. Your back-end DTI divides total monthly debt obligations by gross monthly income. Most Georgia construction lenders cap this at 43–45%.
A household earning $125,000 per year brings in roughly $10,400 per month before taxes. At 43% DTI with moderate existing debt ($700/month), a lender allows approximately $3,072 for a construction loan payment. At current rates, that supports a loan of $455,000–$475,000. Subtract the 20% down payment and you arrive at a total project budget of $415,000–$440,000, roughly the cost to build a 2,100–2,600 sq ft house at mid-range finishes. If you're comparing that budget to current build prices, see our cost to build a house in North Georgia guide.
How Much Does It Cost to Build a House in North Atlanta?
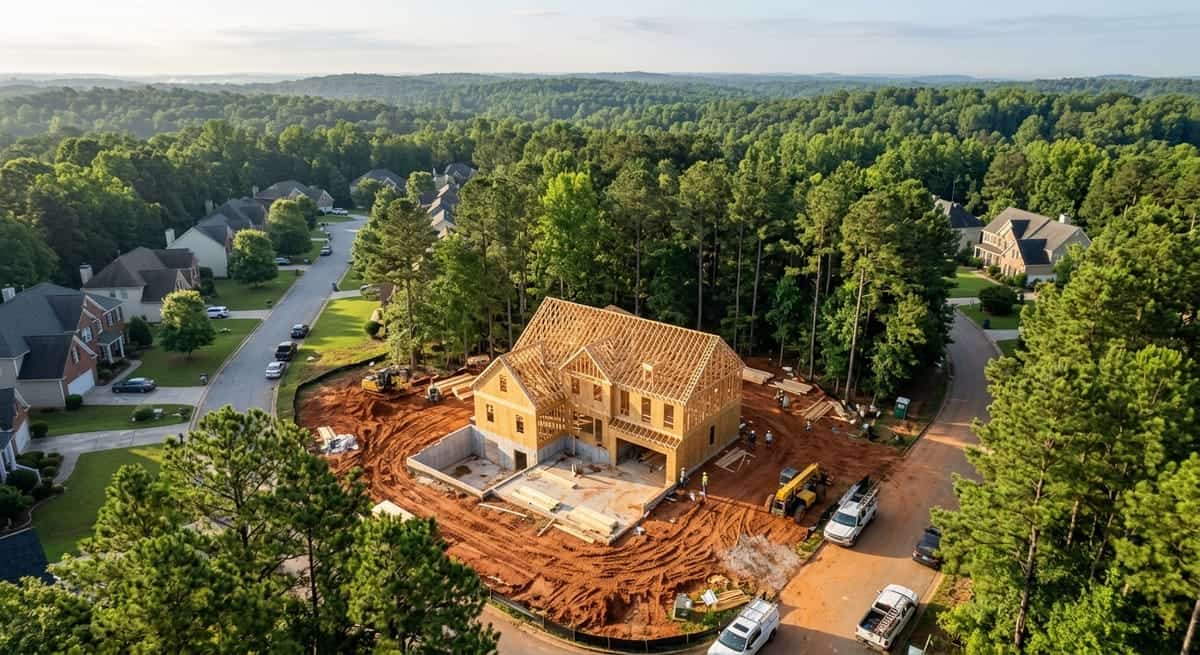
North Atlanta build costs run above national averages. Labor demand, land costs, and Georgia's building code requirements all push the cost to build a house per square foot higher than national sites typically publish. For current per-square-foot figures by community and finish tier, see Artistic Construction's custom home cost guide for North Georgia.
The cost difference between building in Cherokee County versus North Fulton County can run $30,000–$80,000 or more on a comparable home.
| County | Key Areas | Cost Profile |
|---|---|---|
| Cherokee | Canton, Woodstock, Ball Ground | Most competitive |
| Cobb | Kennesaw, Acworth, Marietta | Mid-range |
| Fulton (North) | Alpharetta, Milton, Roswell | Highest |
Full Build Costs Most Builders Don't Mention
Beyond the construction contract, plan for:
- Land clearing and grading: Rocky lots require specialized equipment and costs vary widely.
- Permits and impact fees: Can reach $5,000–$20,000 depending on jurisdiction and home size.
- Architecture and design fees: Generally 5–15% of construction costs.
- Landscaping, driveway, and exterior work: Often excluded from base builder quotes.
- Appliances and window treatments: Frequently omitted from "base price" figures.
For a complete breakdown, see Artistic Construction's guide to hard vs. soft costs in custom home construction.
Budget a 10–20% contingency reserve, treat it as non-negotiable. On a $400,000 build, that means holding $40,000–$80,000 back.
Construction Loan Requirements in Georgia
How Construction-to-Permanent Loans Work
A construction-to-permanent loan funds your build in stages called "draws." The lender releases money as each phase is completed and inspected. During construction, you make interest-only payments on the amount drawn. When the build finishes, the loan converts to a standard 15- or 30-year mortgage. Qualification standards are stricter than a conventional purchase mortgage.
What Georgia Lenders Require in 2026
| Requirement | Typical Standard |
|---|---|
| Credit score | 680 minimum; 700+ for best rates |
| Down payment to build a house | 20–25% |
| Back-end DTI | Under 43–45% |
| Cash reserves | 6–12 months of projected payments |
| Builder approval | Licensed, insured, lender-vetted |
If you already own your lot, that equity can count toward the down payment requirement, a real advantage for Cherokee County buyers who purchased acreage before starting the build process.
For renovation financing options relevant to your planning, see Artistic Construction's Georgia home renovation financing guide.
Ready to find out what your household income can build in Cherokee, Cobb, or Fulton County?
Start with a free estimate from Artistic Construction, a clear-eyed look at what's possible for your budget, timeline, and preferred community.
Frequently Asked Questions
What is the minimum salary to build a house in Georgia?
Most Georgia lenders require a back-end DTI under 43–45%. A household income around $75,000–$85,000 may qualify for a construction loan sufficient for a modest build in Cherokee County. Lower existing debt and stronger credit scores improve qualification meaningfully.
How is a construction loan different from a regular mortgage?
A construction loan funds your build in draw stages with interest-only payments during construction, then converts to a standard mortgage at completion. Expect higher credit score minimums, larger down payments of 20–25%, and verified builder credentials.
What costs do most builder quotes leave out?
Base quotes frequently exclude land clearing, grading, permits, impact fees, architecture fees, landscaping, driveways, appliances, and window treatments. In Cherokee County, impact fees alone can reach $5,000–$20,000. Always budget a 10–20% contingency on top of any quoted figure.
Can lot equity count toward a construction loan down payment in Georgia?
Yes. If you already own your land, most Georgia lenders will count that equity toward the 20–25% down payment requirement, substantially reducing the cash needed at closing.
How long does it take to build a custom home in North Atlanta?
Most custom builds in Cherokee, Cobb, and Fulton counties take 9–14 months from permit approval to certificate of occupancy. Permitting alone can add 4–8 weeks before ground breaks.
What new-construction warranties should I expect?
Georgia law requires a one-year workmanship warranty, a two-year systems warranty covering electrical, plumbing, and HVAC, and a ten-year structural defect warranty. Confirm these minimums in writing before signing any contract.
Planning a project?
Skip the guesswork, get real numbers.
Reading is great. A clear, itemized estimate is better. Tell us what you have in mind.